Chimgan Residence mortgage
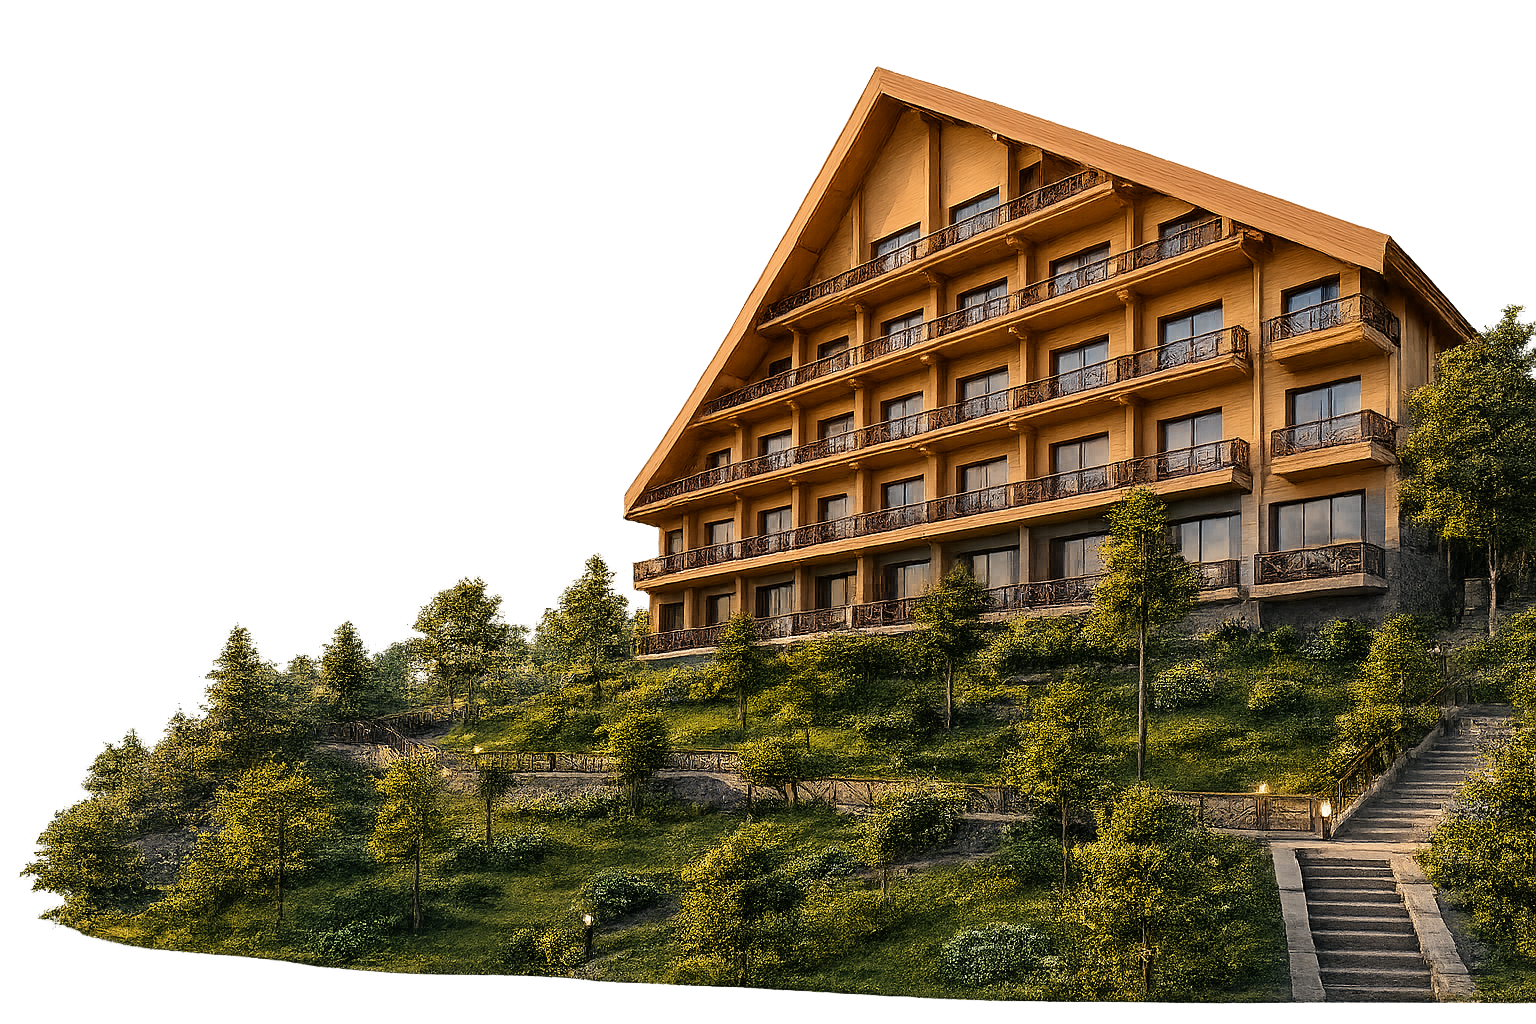
Comfortable living in the picturesque Chimgan Mountains is no longer a dream, but a reality.
Maximum loan amount
Credit rate
Loan term
Down payment

Get a consultation or submit a preliminary application on the website

Choose a property and enter into a sale and purchase agreement with the property developer

Submit the required documents to the Bank, sign the loan agreement and receive the loan proceeds
Passport or ID card
Equity participation agreement in construction
Proof of income (salary, pension, income from individual entrepreneurship, etc.)
Documents relating to the loan security
The loan is available to citizens of the Republic of Uzbekistan who are at least 18 years old on the application date and no older than 60 years on the date of full loan repayment.

SMS
Send an SMS to 2500

At the Bank
At any Bank office

By Card
Through the SQB Mobile app

pre-application?
This application has an introductory function to determine the creditworthiness of the payer and is not an offer contract. By completing the application, you will receive a preliminary decision from the bank on the issue of the mortgage.

Loan purpose:
Financing the purchase of residential property (apartments) at Chimgan Residence, located in the Chimgan mahalla of Bostanlyk District, Tashkent Region, including purchases made through auction.

Maximum loan amount:
Up to UZS 1.5 billion.
Down payment:
At least 20% of the property value.

Grace period:
Up to 6 months under a declining-balance repayment schedule.

Repayment schedule:
Annuity or declining-balance.
Source of financing:
The Bank’s own funds.

Loan security:
Mortgage over the property purchased with the loan proceeds.
Security requirements:
- The loan-to-value ratio must not exceed 80%;
- The value of the security must be at least 125% of the loan amount.
For parties related to the Bank:
- The value of the security must be at least 130% of the loan amount;
- An insurance policy may be provided to cover the unsecured portion.
Insurance of the unsecured portion:
The insurance agreement and insurance policy must cover the entire loan term.
Additional terms:
The property may be purchased:
- Under a sale and purchase agreement with the Chimgan Residence contracting organisation;
- Through auction.
Legal basis:
Resolutions of the Cabinet of Ministers of the Republic of Uzbekistan No. 451 dated 18 July 2025 and No. 574 dated 9 September 2025.
Down payment: 50%.
Down payment: 30%.
Down payment: 20%.


- citizenship of the Republic of Uzbekistan;
- between 18 and 60 years of age, inclusive, on the application date;
- a source of income sufficient to make the monthly payments;
- no current overdue debt;
- a debt-service-to-income ratio of no more than 50%;
- the applicant’s credit history is reviewed for the preceding 24 months. The loan application will be rejected if three or more instances of payment arrears exceeding 90 days are identified.
-
A self-employed applicant may verify their income using:
- information on funds credited to bank accounts or cards during the preceding six months;
- information provided by the state tax authorities;
- an income declaration.
Income is calculated after the deduction of taxes.
Self-employment income is not accepted for a co-borrower.
- The same requirements regarding age, income and the absence of overdue debt apply as for the primary borrower.
- An identity document, which may be provided digitally through the Unified Portal of Interactive Public Services.
- Income information for the preceding six months, which may be obtained electronically by the Bank.
- Certificate of registration as a self-employed individual, if required.
- Property sale and purchase agreement with the Chimgan Residence contracting organisation.
- For purchases made through an auction, confirmation of the successful bid and payment.
- Documents relating to the loan security, including an independent appraisal report if required.
The Bank may request additional documents in accordance with applicable law.
Notarial fees for executing the property sale and purchase agreement;
Costs associated with preparing cadastral documents and registering ownership rights;
Costs of insurance against the risk of loan default, if required.
Issued for the purchase of apartments from the primary market
Make everyday payments using the convenient app
 Application sent
Last updated date: 16.10.2026 11:29